- Issuing authority
- Federal Tax Authority
- Jurisdiction
- United Arab Emirates
- Publication date
- October 9, 2026
- Effective date
- October 1, 2026
- Stage
- Final rule
- Official document
- FTA Decision No. 13 of 2026, Cabinet Decision No. 149 of 2026, FTA Decision No. 17 of 2026
- Official source
- legarithm.io
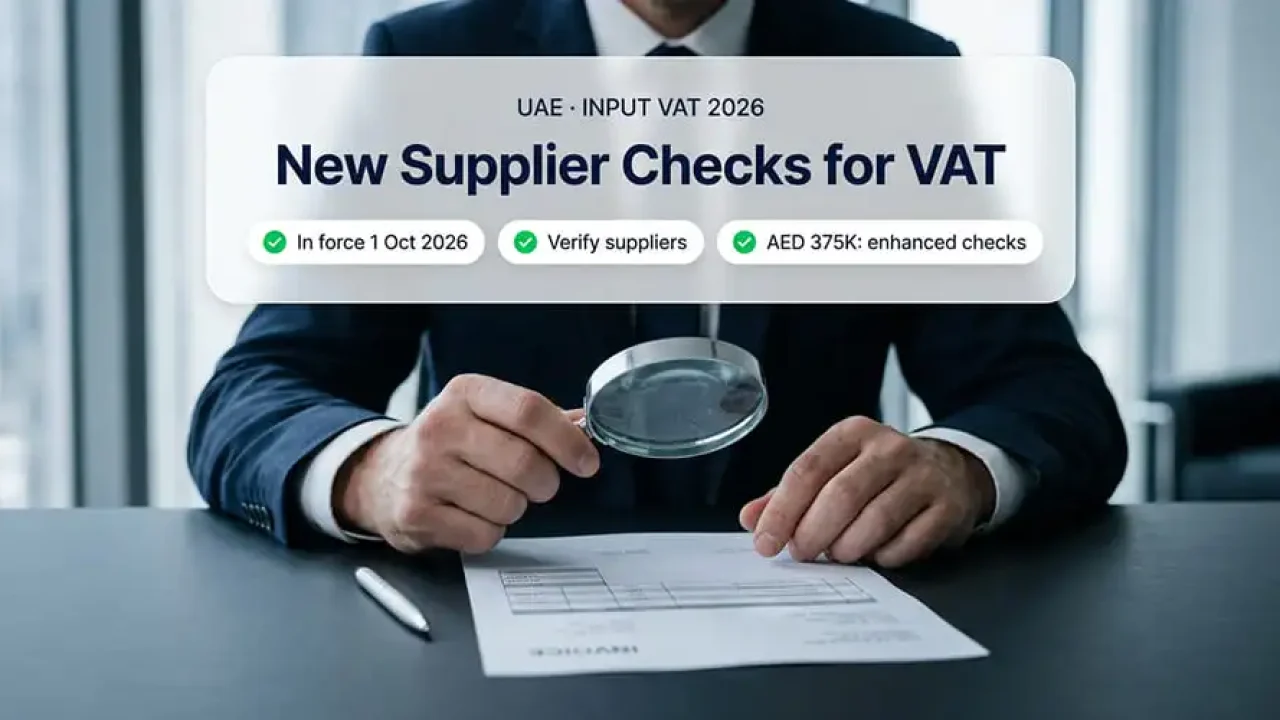
Under UAE Federal Tax Authority (FTA) Decision No. 13 of 2026, effective 1 October 2026, holding a valid tax invoice is no longer sufficient to recover input VAT. Businesses are required to perform structured due diligence on suppliers and supplies to verify legitimacy and prevent exposure to supply-chain tax evasion. The measure implements Article 54 bis of the VAT Law, introduced by Federal Decree-Law No. 16 of 2025, which allows the FTA to deny input tax recovery if a supply is tied to tax evasion and the buyer knew or should have known.
The regulatory framework exempts supplies below AED 10,000 (excluding VAT) from detailed checks, provided total supplies from that vendor remain under AED 100,000 across a rolling 12-month period. Once annual transactions exceed AED 100,000, full standard checks apply, covering supplier incorporation documents, verification of representatives, and confirmation of an actual place of business.
For suppliers exceeding AED 375,000 in rolling 12-month transactions, companies must carry out enhanced due diligence. This includes securing written confirmation from a UAE-licensed bank that the vendor holds the settlement account, as well as conducting public reputation and risk screenings. Supplier verifications must be documented during onboarding and renewed at least every 12 months, or immediately if risk indicators arise.
In related changes, Cabinet Decision No. 149 of 2026 amended the VAT Executive Regulation to restrict input tax recovery on cash payments exceeding a future threshold set by the Minister of Finance. Additionally, FTA Decision No. 17 of 2026 defined six specific scenarios under which input VAT on employee benefits—such as business transport, job-related mobile and internet plans, and mandatory on-site accommodation—remains recoverable.
Sources
- Legarithm · 2026-10-09