- Issuing authority
- UAE Cabinet
- Jurisdiction
- United Arab Emirates
- Publication date
- November 13, 2026
- Effective date
- November 30, 2026
- Stage
- Final rule
- Official document
- Cabinet Decision No. 142 of 2024 and amendments to Federal Decree-Law No. 47 of 2022
- Official source
- www.arabianbusiness.com
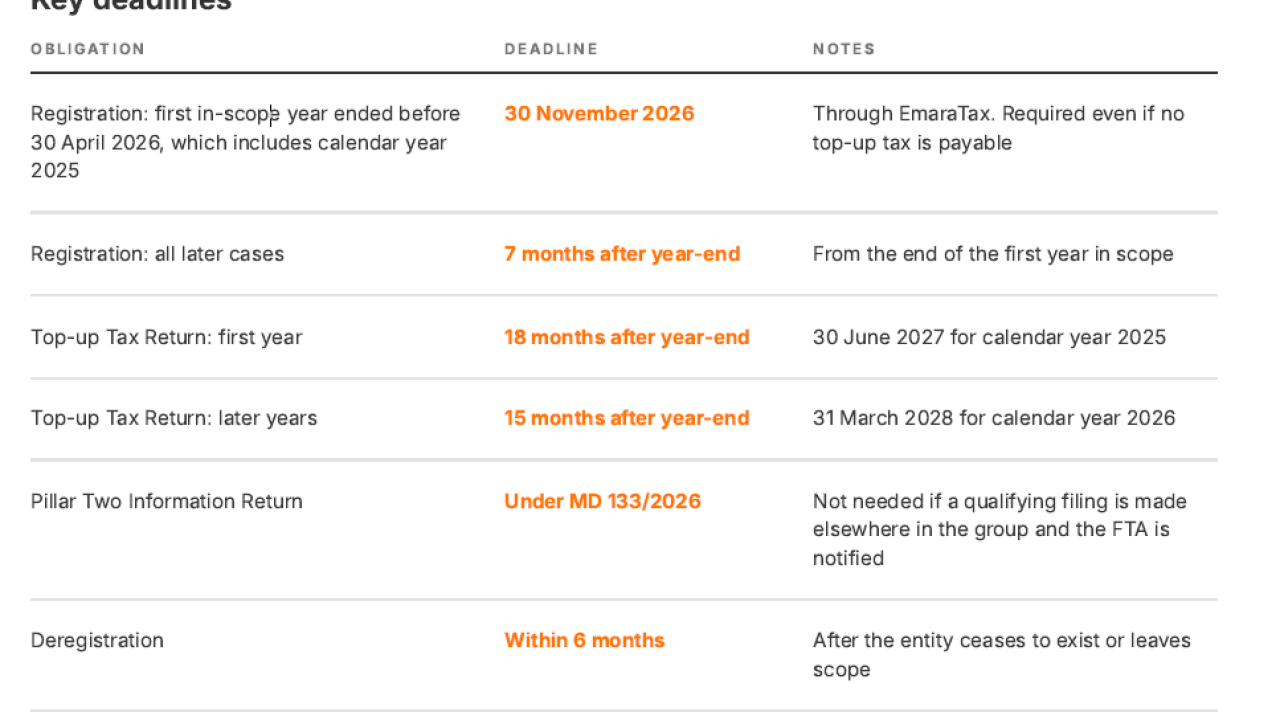
A regulatory analysis published by IR Global on November 13, 2026, outlines compliance requirements and deadlines under the United Arab Emirates Domestic Minimum Top-up Tax (DMTT), including a registration cut-off set for November 30, 2026.
The DMTT framework is implemented through Cabinet Decision No. 142 of 2024 and amendments to Federal Decree-Law No. 47 of 2022, aligning national tax law with the OECD Pillar Two global minimum tax regime. The regulations apply to multinational enterprise groups with annual consolidated revenues of €750 million or more in at least two of the prior four fiscal years.
Under the rules, Qualifying Free Zone Persons that previously benefited from a 0% corporate tax rate may now face a top-up tax up to the 15% minimum rate.
Affected multinational entities operating in the UAE must put systems in place to calculate and report adjusted covered taxes, deferred taxes, and substance-based income exclusions relating to payroll and tangible assets.
Sources
- IR Global · 2026-11-13