- Issuing authority
- Federal Tax Authority
- Jurisdiction
- United Arab Emirates
- Stage
- Final rule
- Official document
- Corporate Tax Registration Penalty Waiver Guidance
- Official source
- www.daftra.com
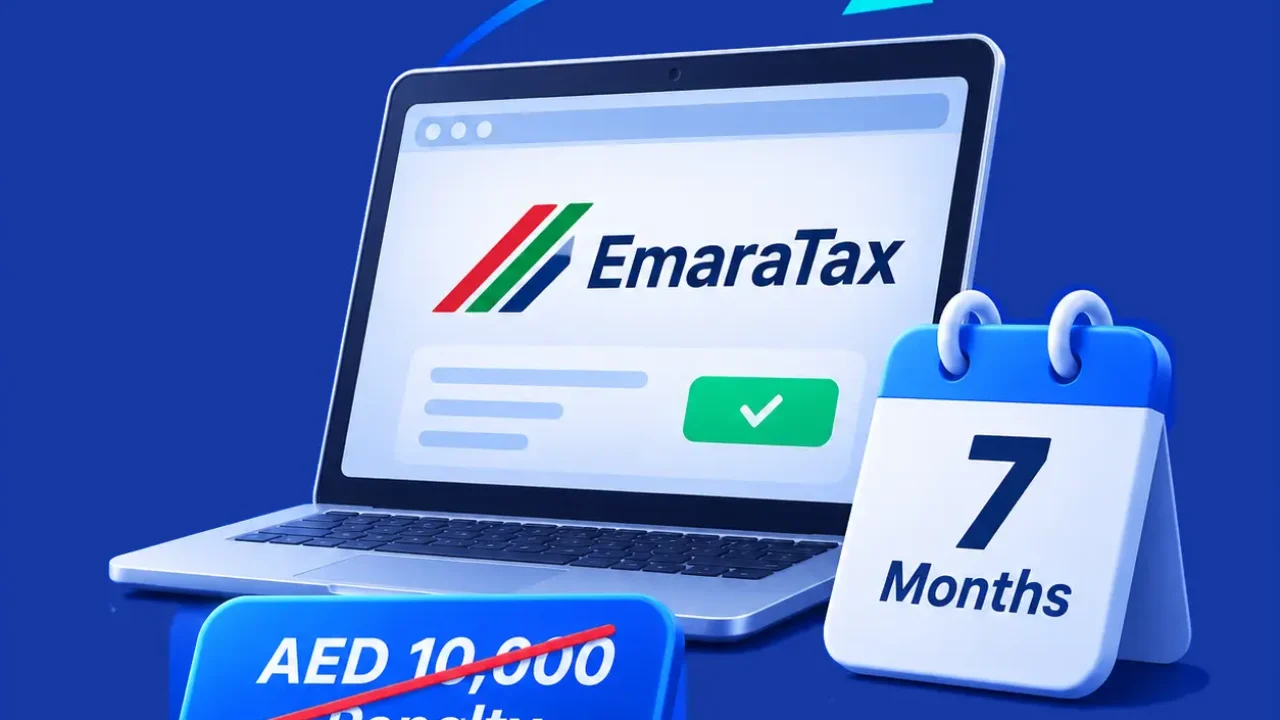
The UAE has clarified operational criteria for an administrative relief initiative that waives the AED 10,000 fine for late Corporate Tax registration. According to guidance published by Daftra, the measure applies specifically to the late registration penalty and does not constitute a general tax amnesty or eliminate the obligation to register and pay tax.
To qualify for the penalty waiver, taxable entities must file their initial Corporate Tax return within seven months following the end of their first tax period. For certain exempt entities required to register, the annual declaration must similarly be filed within seven months from the conclusion of the first financial year. This seven-month requirement is an early-filing condition specific to the penalty waiver, distinct from the standard statutory filing deadline of nine months.
Eligible categories include natural persons conducting taxable business activities, juridical persons, members of tax groups, qualifying public benefit entities, and certain exempt persons. Taxpayers who have already incurred or paid the AED 10,000 fine remain eligible; upon satisfying the conditions, the Federal Tax Authority generally credits the paid amount to the taxpayer's EmaraTax account before a refund can be claimed.
Taxpayers generally do not need to lodge a separate application to obtain the waiver, but must meet the accelerated filing timetable alongside proper registration. The initiative is intended to encourage proper registry documentation and support SME compliance across the country.
Sources
- Daftra · 2026-11-16